What Makes US Stock Tick Data Indispensable for Quantitative Research? Python Realtime Integration Guide
In my daily quantitative research and market strategy development, I primarily rely on standardized aggregated candlestick datasets, including 1-minute, hourly, and daily charts. These pre-processed market data files feature neat structures and low development thresholds, perfectly fitting basic tre
What Makes US Stock Tick Data Indispensable for Quantitative Research? Python Realtime Integration Guide
In my daily quantitative research and market strategy development, I primarily rely on standardized aggregated candlestick datasets, including 1-minute, hourly, and daily charts. These pre-processed market data files feature neat structures and low development thresholds, perfectly fitting basic tre
How to Standardize Timestamp Formats for Multi-Currency Forex API Data?
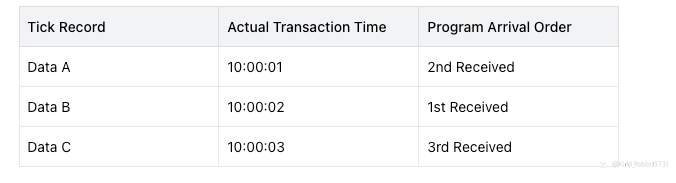
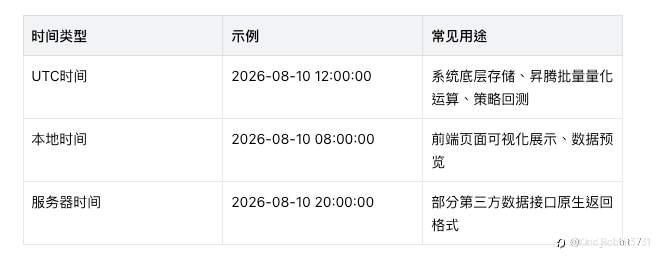
During the iteration and maintenance of our forex market analysis module, I encountered a tricky and hard-to-diagnose data problem. When processing synchronous data collection for multiple forex trading pairs, all price-related fields were completely normal without abnormal fluctuations or missing v
How to Standardize Timestamp Formats for Multi-Currency Forex API Data?
During the iteration and maintenance of our forex market analysis module, I encountered a tricky and hard-to-diagnose data problem. When processing synchronous data collection for multiple forex trading pairs, all price-related fields were completely normal without abnormal fluctuations or missing v
Can Order‑book Snapshot Fix Your Misleading Historical Backtest Results?
Most quantitative traders and developers rely heavily on candlestick and transaction data when running historical market replays. These basic data types are easy to obtain and seem reliable enough for daily strategy verification. However, once you upgrade your research to order-book level granularit