


MARKET REVIEW FOMC FOREX RATES
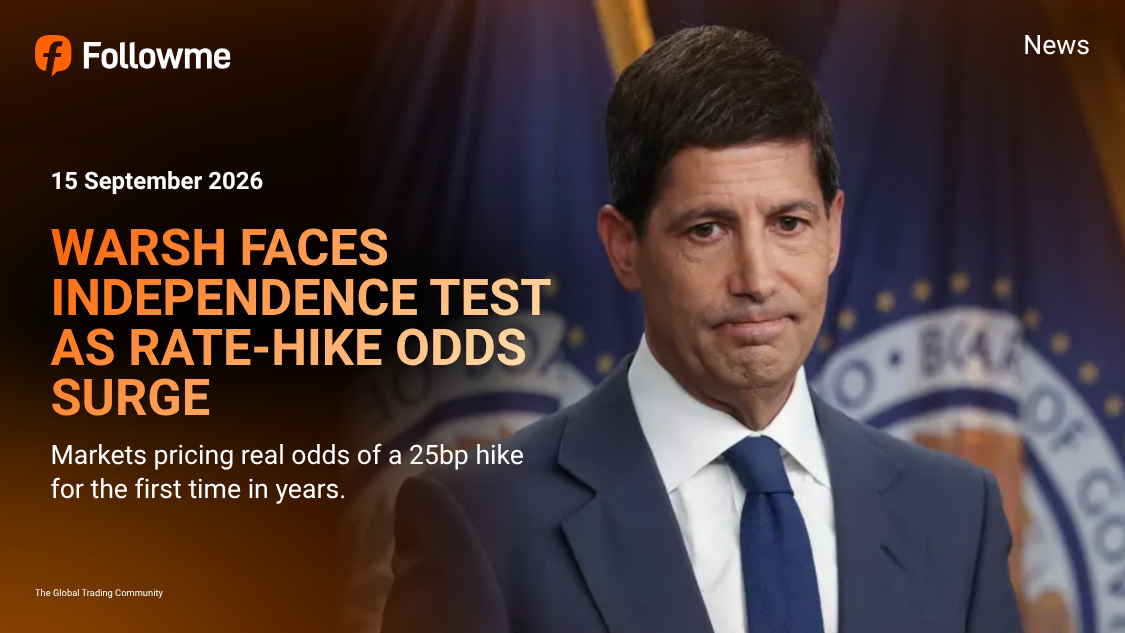
Fed Chief Warsh Faces Independence Test as Rate-Hike Odds Surge
Followme News Desk | September 15, 2026
Executive Summary
- The Fed's two-day policy meeting concludes Wednesday, Sept. 16, 2026, with a decision due at 1800 GMT (2:00 p.m. ET) — markets are pricing real odds of a 25bp hike, not a cut, for the first time in years.
- CME FedWatch puts hike odds in the high-50s to mid-60s percent range; Kalshi and Polymarket show a closer-to-even split, making this a genuine coin-flip decision.
- The repricing follows a hawkish Jackson Hole speech from Fed Chair Kevin Warsh, against a backdrop of core PCE inflation near 3.3% and an oil-driven gasoline price spike (to ~$4.32/gallon from $3.18 a year ago).
- Treasury yields have already moved sharply — the 10-year briefly hit 5% for the first time since 2023 — while a separate AI-linked equity selloff (Nvidia, SoftBank) has added a stagflationary tilt to markets ahead of the decision.
- A public rift between Warsh and President Trump, who wants lower rates, has turned this into a test of Fed independence; Treasury Secretary Scott Bessent has publicly given Warsh room to act, citing bond-market discipline.
- Three scenarios are in play — confirmed hike, hawkish hold, dovish surprise — each with distinct implications for the dollar, yields, equities, EM/Asian FX, gold, oil and crypto (detailed below).
Market Review
The Federal Reserve opens its two-day policy meeting on Tuesday, Sept. 15, 2026, under conditions few traders anticipated as recently as a month ago: rather than debating the size of a rate cut, markets are pricing real odds that the central bank raises rates when it announces its decision at 1800 GMT (2:00 p.m. ET) on Wednesday, Sept. 16 — the first such move in years.
CME Group's FedWatch tool shows the probability of a 25-basis-point hike in the high-50s to mid-60s percent range, up from near zero a month earlier. Prediction markets Kalshi and Polymarket put the odds closer to 50-50, reflecting a decision that traders and economists describe as a genuine coin flip.
The repricing follows a hawkish turn by Fed Chair Kevin Warsh, who was appointed by President Trump in May. Speaking at the Kansas City Fed's Jackson Hole symposium in late August, Warsh said the central bank "must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed," and suggested financial conditions were not restrictive enough to bring that about.
Core personal consumption expenditures inflation, the Fed's preferred gauge, was running around 3.3% in early August, well above the central bank's 2% target. Price pressure has since been compounded by a jump in oil prices after intensified Houthi attacks in the Red Sea and damage to a Saudi pipeline expected to remain offline for weeks. U.S. retail gasoline prices have risen to roughly $4.32 a gallon from $3.18 a year earlier.
Bond Market Already Moving
Treasury yields have repriced sharply since Warsh's remarks. Assets that moved ahead of the meeting include:
- U.S. 10-year Treasury yield: briefly touched 5% this week, the first time since 2023, before settling near 4.95%.
- U.S. 2-year Treasury yield: rose to its highest level since late July, in the immediate aftermath of Warsh's Jackson Hole speech, reflecting its greater sensitivity to near-term policy shifts.
- Nvidia: shares fell as part of a broader pullback in AI-linked equities, following warnings from industry executives over AI safety risks.
- SoftBank: among the sharpest decliners, after comments attributed to OpenAI Chief Executive Sam Altman signaled the company would delay its planned initial public offering.
- Broader equity tape: traders described a stagflationary tilt developing as rising yields and the AI-linked selloff moved in tandem — a combination not seen elsewhere in this cycle.
Political Backdrop
The prospect of a hike has set up a public tension between Warsh and the president who appointed him. Trump has repeatedly called for lower rates, while Warsh's public remarks since Jackson Hole have pointed the other way.
Treasury Secretary Scott Bessent sought to lower the temperature this week, telling reporters the bond market "has taken down more governments than howitzers" and saying he expected Warsh to act independently to balance inflation and growth. Analysts said the comments amounted to political cover for the Fed to raise rates if incoming data warranted it, with congressional midterm elections in November keeping the question of central bank independence under scrutiny.
What Traders Are Watching
The rate decision and Fed projections are due Wednesday, followed by a press conference with Warsh. Market participants said three outcomes are in play:
- Confirmed hike: would likely extend dollar strength, push front-end yields higher, and add pressure to an already fragile equity tape, with emerging-market and Asian currencies most exposed to renewed dollar strength.
- Hold with hawkish guidance (what some traders termed a "hawkish pause"): would leave yields elevated and keep a hike priced in for a subsequent meeting, without an immediate shock.
- Dovish surprise (hold rates, softer tone): would run counter to Warsh's messaging since Jackson Hole and could trigger a relief rally in equities and bonds, though analysts said it would raise fresh questions about political influence over the central bank.
Traders said the dot plot and the tenor of Warsh's press conference — particularly any direct response to questions about political pressure from the White House — were likely to move markets as much as the rate decision itself.
Assets to Watch After the Decision
Analysts and traders identified the following as most likely to react in the hours after Wednesday's announcement:
- U.S. dollar index: likely to strengthen on a confirmed hike or hawkish hold, as the rate path diverges further from peers; a dovish surprise would send it lower.
- U.S. Treasury yields (2-year, 10-year): a hike would push yields higher across the curve, with the 10-year risking a retest of the 5% level; a dovish surprise would likely pull yields back from recent highs.
- U.S. equities, particularly AI-linked names: already under pressure from the separate AI selloff, a hike would add to downside risk for Nasdaq-listed growth stocks; a dovish surprise could spark a relief rally, though traders cautioned any bounce may be short-lived given the unresolved AI-valuation concerns.
- Emerging-market and Asian currencies: among the most exposed to a stronger dollar, with analysts flagging the Thai baht and Vietnamese dong as regional currencies to watch alongside broader EM FX.
- Gold: typically inversely correlated with real yields; a hike would likely weigh on prices, while a dovish surprise or renewed geopolitical escalation could support a rebound.
- Oil: less directly tied to the rate decision itself, but a hawkish outcome that strengthens the dollar could cap further gains even as Middle East supply risks persist.
- Bitcoin and risk-sensitive crypto assets: traders said these would likely trade in line with broader risk sentiment, pressured by a hike and higher yields, supported by a dovish surprise.
Follow us for daily market insights, analysis, and the tools you need to trade with confidence.
Want to stay ahead of major macro developments that move the market? 👉 Follow Followme and check out the Weekly Economic Calendar
September 15, 2026 | This report is for informational purposes only and does not constitute financial advice. © 2026 Followme News
Download Followme Application
Follow us on:


면책 조항: 본 게시글에 표현된 견해는 전적으로 작성자의 견해이며 Followme의 공식 입장을 대변하지 않습니다. Followme는 제공된 정보의 정확성, 완전성 또는 신뢰성에 대해 책임을 지지 않으며, 서면으로 명시적으로 언급되지 않는 한 해당 내용을 기반으로 취해진 어떠한 조치에 대해서도 책임을 지지 않습니다.

